Allowance for Kids: How Much and How to Start Right
Discover how to implement an effective allowance for kids, including amounts, starting tips, and practical advice for families.

In this article
Key takeaways
- Establish a clear allowance amount based on age.
- Involve your child in discussions about money management.
- Adjust allowances as children grow and learn.
- Use the allowance as a teaching tool for saving and spending.
As a parent, teaching your child about money management is one of the most important lessons you can impart. An allowance for kids can be an effective way to introduce them to the concepts of earning, saving, and spending wisely. While the idea of giving children money may seem simple, determining how much to give and how to start can be a bit more complex. This guide aims to provide you with the necessary insights to set up an effective allowance system that works for your family.
Understanding the nuances of allowance can help you navigate this financial teaching tool effectively. Each family has its own values, financial circumstances, and parenting styles, and your approach to allowance should reflect your unique family dynamics. In this article, we’ll explore how much allowance is appropriate for different age groups, practical steps for starting an allowance, and tips for making the experience educational and enjoyable for your children.
Ultimately, the goal is to help your child develop a healthy relationship with money that will serve them well throughout their lives. Let’s dive into the details of setting up an allowance for kids that will benefit both you and your child.
Why Give an Allowance?
Providing an allowance serves multiple purposes. First, it fosters independence and responsibility. When children manage their own money, they learn essential life skills such as budgeting, prioritizing spending, and saving for future goals. Allowance can also help children understand the value of money. Instead of simply being given what they want, they learn that money must be earned and managed wisely.
Additionally, teaching financial literacy at a young age lays the groundwork for future financial success. According to the American Academy of Pediatrics, introducing financial concepts early can lead to better decision-making skills later in life. This foundation can help children avoid common financial pitfalls, such as excessive debt or poor saving habits.
Moreover, an allowance can serve as an opportunity for families to bond over financial discussions. You can use it as a chance to talk about your family’s values around money, making the subject less taboo and more approachable. This can create an open dialogue about finances that lasts a lifetime.
How Much Should You Give?
Determining the right allowance amount can depend on several factors, including your family’s financial situation, your child’s age, and the purpose of the allowance. While there is no one-size-fits-all answer, many experts recommend the following guidelines:
- Ages 4-6: $1 per week for each year of age (e.g., $4-$6 per week).
- Ages 7-9: $2 per week for each year of age (e.g., $14-$18 per week).
- Ages 10-12: $3 per week for each year of age (e.g., $30-$36 per week).
- Ages 13-15: $5 per week for each year of age (e.g., $65-$75 per week).
These amounts are just suggestions. You can adjust based on your family’s specific circumstances. It’s also essential to consider what expenses your child will be responsible for. If your child is expected to pay for certain activities or items, you may want to increase their allowance.
Another approach is to tie the allowance to chores or specific responsibilities. This can help children understand the connection between work and earning money. If you choose this route, be clear about expectations and which chores are eligible for payment.
How to Start an Allowance
Starting an allowance can feel daunting, but it can be a smooth process with the right approach. Here are some practical steps to help you begin:
- Have a Family Discussion: Before implementing an allowance, discuss it as a family. Explain the purpose of the allowance and how it can help your child learn about money management. Encourage your child to express their thoughts and feelings about receiving an allowance.
- Set Clear Guidelines: Outline how much the allowance will be, how often it will be distributed, and any responsibilities attached to it. Make sure your child understands the rules, including any potential penalties for not fulfilling their obligations.
- Create a Budget Together: Once the allowance is established, sit down with your child to create a simple budget. Use this opportunity to discuss the importance of saving and spending. You can help them set short-term and long-term savings goals.
- Monitor Progress: Regularly check in with your child to see how they are managing their funds. Encourage them to track their spending and saving. This can be a valuable learning experience for them.
By taking these steps, you can ensure that your child’s allowance experience is positive and educational. Remember, the goal is to equip them with the tools they need to manage money effectively.

Teaching Money Management Skills
The allowance is not just about giving money; it’s an opportunity to teach your child critical money management skills. Here are some essential concepts to cover:
- Saving: Encourage your child to save a portion of their allowance. You can introduce them to savings accounts or a piggy bank. Teach them about interest and how savings can grow over time.
- Spending Wisely: Discuss the difference between needs and wants. Help them understand the importance of thoughtful spending. You can even establish a
Understanding the Psychological Impact of Allowance
Building a Sense of Responsibility
When children receive an allowance, they learn about the importance of responsibility. It is not merely about managing money but also about understanding the consequences of their spending choices. By handling their own finances, children begin to connect their actions with outcomes, which is a crucial aspect of emotional development. This responsibility can extend beyond money, fostering a sense of accountability in other areas of their lives.
For instance, if a child chooses to spend their allowance on a toy instead of saving for a more significant purchase, they might feel regret when they realize they could have bought something they wanted more. This process of making choices and experiencing their results can teach valuable life lessons.
Boosting Self-Esteem and Independence
Allowances can significantly boost a child’s self-esteem. As they manage their finances, they gain a sense of independence that contributes to their confidence. When children realize they can make their own financial decisions, they feel empowered and capable. This newfound independence can lead to a stronger sense of self-worth and competence, which is essential for their overall development.
- Encourage decision-making: Let children make choices about spending their allowance.
- Celebrate successes: Acknowledge when they make wise spending choices.
- Learn from mistakes: Help them understand that mistakes are part of the learning process.
Understanding Emotional Spending
Children may not initially understand the difference between needs and wants, leading to emotional spending. Teaching them about emotional spending is vital in helping them develop healthy financial habits. Emotional spending often occurs in response to feelings such as boredom, sadness, or anxiety. By recognizing these triggers, children can learn to pause and assess their feelings before they decide to spend their allowance impulsively.
Parents can guide their children in identifying their emotions and finding alternative coping strategies. For example, if a child feels bored and wants to spend money on snacks, parents might suggest more productive activities, such as reading a book or engaging in a hobby. This approach not only helps them manage their money but also fosters emotional intelligence.
A couple sits at a table managing domestic finances, evaluating documents and using a smartphone (Photo by Vodafone x Rankin everyone.connected on Pexels) Incorporating Savings Goals into Allowance
Setting Short-term and Long-term Goals
Incorporating savings goals into the allowance system can teach children the importance of planning for the future. Encouraging children to set both short-term and long-term savings goals can help them understand the value of patience and delayed gratification. Short-term goals may include saving for a small toy, while long-term goals could involve saving for a bike or a special outing.
Parents can assist children in identifying how much they need to save each week to reach their goals. This practice not only teaches financial planning but also instills a sense of achievement when they reach their targets.
- Short-term goals: Encourage saving for items they desire within a few weeks.
- Long-term goals: Help them establish plans for larger purchases over a few months.
- Goal tracking: Create a visual representation, like a savings chart, to track progress.
Creating a Savings System
Establishing a savings system can make the process of saving more tangible and organized. Parents can introduce concepts like different jars or envelopes labeled for spending, saving, and sharing. This physical representation of money can help children visually understand where their funds are allocated, reinforcing the lessons learned about budgeting and prioritizing expenses.
Additionally, parents can encourage children to save a specific percentage of their allowance, teaching them the importance of saving a portion of their income consistently. This practice will help them develop good financial habits early on.
Encouraging Philanthropy and Sharing
Allowances can also serve as an opportunity to teach children about the importance of giving back. Encouraging children to allocate a portion of their allowance for charitable donations or community support can foster empathy and social responsibility. Parents can discuss various causes that resonate with their children, allowing them to choose where to contribute their funds.
This practice not only teaches financial literacy but also instills the value of kindness and generosity in children, making them aware of the needs of others. Engaging children in discussions about why giving is essential can further enhance their understanding of community and compassion.
- Choose a cause: Help them select a charity or community initiative they care about.
- Set a giving goal: Encourage them to aim for a specific amount to donate each month.
- Discuss the impact: Talk about how their contributions can help others.
Adapting Allowance to Age and Maturity
Tailoring Amounts to Developmental Stages
As children grow, their understanding of money and financial responsibility evolves. Therefore, parents should consider adjusting the allowance amounts based on their child’s age and maturity level. Younger children may require smaller amounts while they learn basic concepts of currency, while older children can handle larger sums as they take on more complex financial responsibilities.
For instance, toddlers may receive a weekly allowance of a few coins to introduce them to the idea of money, while pre-teens may be given a more substantial allowance to manage their expenses related to school activities, outings with friends, and personal items.
- Toddlers: Introduce coins and basic concepts of money.
- Elementary school: Increase amounts to cover small purchases and teach budgeting.
- Teens: Provide a more significant allowance to manage personal finances and expenses.
Encouraging Financial Discussions as They Mature
As children mature, it becomes increasingly important to engage them in financial discussions. Parents should create an open environment where children feel comfortable discussing money, budgeting, and financial decisions. This practice can help demystify financial topics and encourage children to ask questions and seek guidance.
Involving them in family budgeting meetings or discussions regarding larger expenses, such as vacations or home purchases, can provide them with real-world experience in financial decision-making. These conversations will prepare them for adulthood and help them understand the complexities of financial management.
Revisiting and Adjusting the Allowance System
Parents should periodically revisit the allowance system to ensure it remains effective and relevant as their children grow. What works for a child at one age may not be suitable as they enter new developmental stages. Regular discussions about the allowance allow parents to gauge their child’s understanding and adjust accordingly.
For instance, if a child shows increased maturity in handling money, parents might consider offering them a greater allowance or more responsibilities regarding their finances. Conversely, if a child struggles with their allowance, it may be time to simplify the system or provide additional guidance.
- Regular assessments: Schedule discussions about the allowance every few months.
- Adjust based on maturity: Be open to increasing or decreasing amounts as needed.
- Solicit feedback: Ask children how they feel about the allowance system and any changes they might suggest.
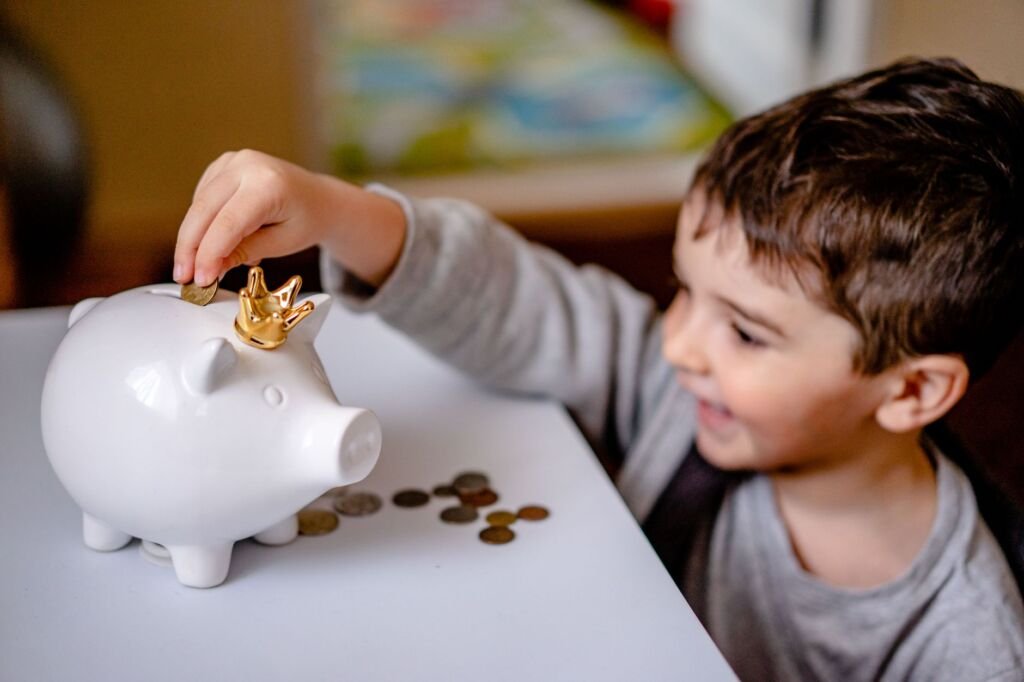
Young boy smiling while saving money in a crowned piggy bank, demonstrating financial responsibility (Photo by Atlantic Ambience on Pexels) Linking Allowance to Responsibilities
Defining Age-Appropriate Chores
One effective way to structure an allowance is to tie it to age-appropriate chores. For younger children, this may include simple tasks such as tidying up their toys or helping with meal preparation. As they grow older, chores can evolve to include tasks like doing laundry or cleaning their rooms. This not only teaches responsibility but also instills the value of earning their allowance through hard work.
- Preschool (3-5 years): Put away toys, help set the table.
- Elementary (6-10 years): Make their beds, feed pets.
- Pre-teen (11-13 years): Vacuum, do laundry.
- Teen (14+ years): Grocery shopping, meal prep.
Establishing a Chore Chart
Creating a chore chart can help visualize responsibilities and allowances. A chore chart fosters accountability, allowing kids to see what tasks they are responsible for and how these relate to their allowance. Parents can use stickers or checkmarks to indicate completed tasks, which can motivate kids to finish their chores. The chart can be tailored to include daily, weekly, or monthly tasks.
Strategies for Encouraging Savings
Creating a Savings Challenge
Incorporating savings challenges can be a fun and engaging way to motivate children to save. For example, parents can set a goal for their child to save a specific amount within a certain timeframe, offering a small bonus when they reach their goal. This creates excitement around saving and teaches children the importance of delayed gratification.
Visualizing Savings Progress
Using jars or digital apps to visualize savings can enhance a child’s understanding of financial goals. Children can have separate jars for spending, saving, and charity. Watching their savings grow can be incredibly satisfying and encourages them to continue saving. Apps can provide a modern twist, allowing children to track their progress digitally.
Addressing Fairness and Equity
Discussing Financial Equity Among Siblings
When multiple children are involved, it is essential to address issues of fairness and equity in allowances. Parents should have open discussions about how allowances may differ based on age, responsibilities, or specific needs. This helps children understand that fairness does not always mean equal, but rather equitable based on individual circumstances.
Encouraging Empathy Through Charitable Giving
Incorporating charitable giving into the allowance framework can foster empathy and social responsibility. Encourage children to set aside a portion of their allowance for a cause they care about. This not only teaches financial management but also instills the value of giving back to the community.
Related reading: Homework Battles: Making Evenings Calmer for Families and Helping Your Shy Child Build Lasting Friendships.
Trusted sources: HealthyChildren.org (American Academy of Pediatrics), HealthyChildren.org: Toddler.
Frequently Asked Questions
At what age should I start giving my child an allowance?
You can start giving an allowance as early as age four, using simple amounts that reflect their age. This helps introduce them to money concepts gradually.
What if my child wants to spend their allowance immediately?
It's normal for children to want to spend quickly. Encourage them to think about their purchases and consider waiting for larger goals to teach patience and saving.
How can I help my child understand the difference between needs and wants?
Engage in discussions about their spending choices and ask guiding questions. Help them categorize items and reflect on their priorities.
Should I increase the allowance as my child gets older?
Yes, as your child matures and takes on more responsibilities, it's appropriate to adjust their allowance to reflect their growing financial needs and understanding.
The Bottom Line
Establishing an allowance for your child can teach them valuable money management skills while fostering independence and responsibility. Tailoring the allowance to their age and maturity ensures that it remains effective and relevant. Regular discussions about finances can strengthen your family's bond and help your child develop a healthy relationship with money.
Was this article helpful?
Thanks for letting us know! Your feedback helps us make our articles better.

Writer at Apparently a Parent, covering the everyday joys and challenges of raising a family.
One Response